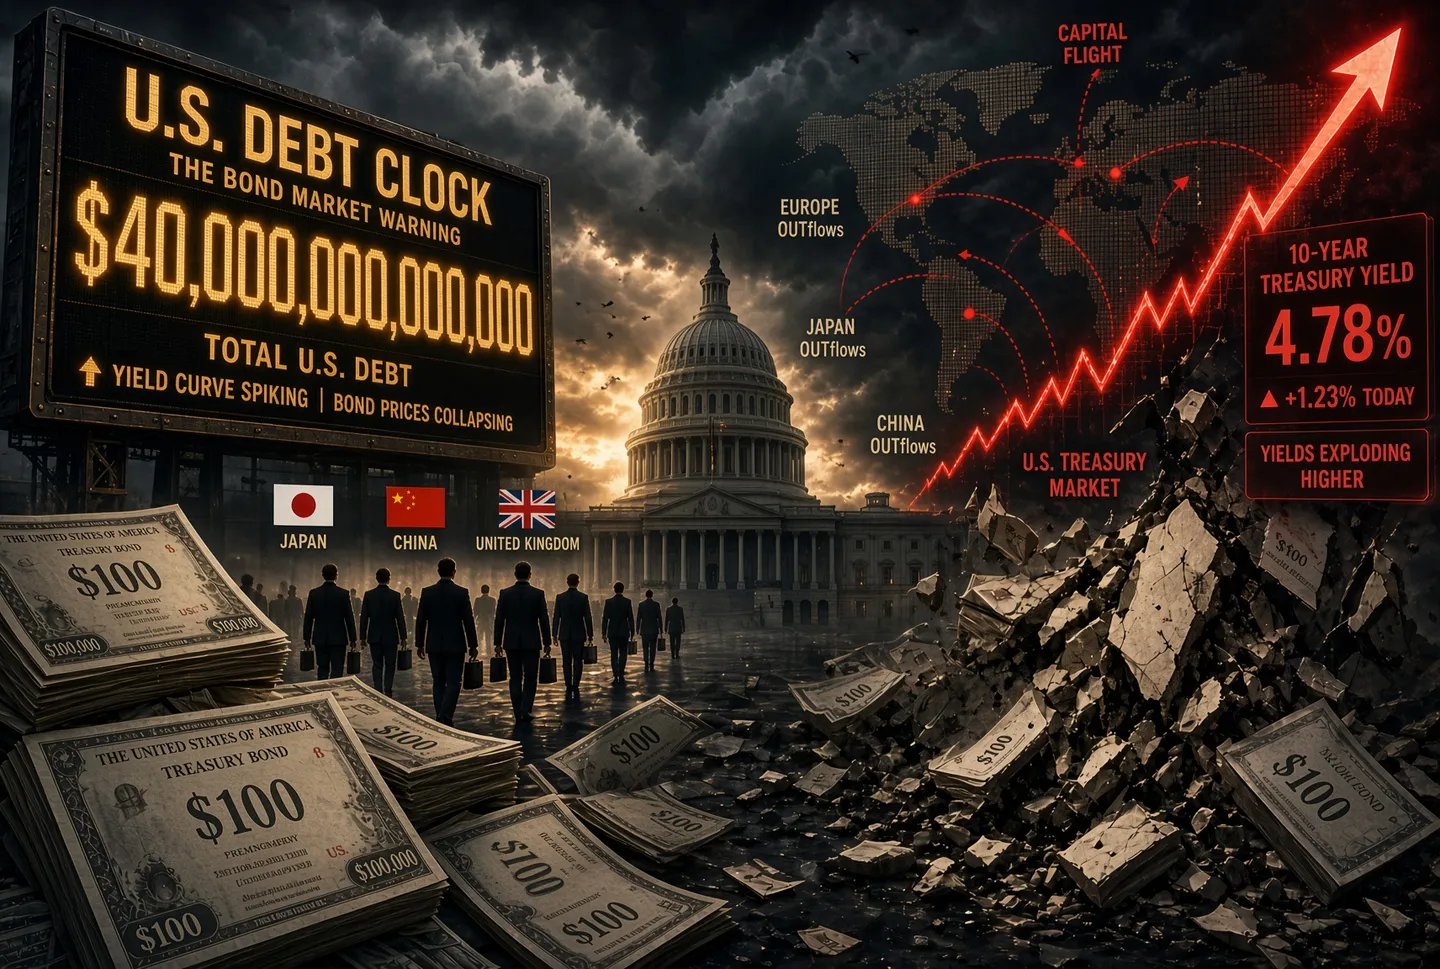


US Treasury bonds, long considered the bedrock of global financial stability, are experiencing a period of significant volatility. As America’s national debt climbs past a record $40 trillion, major foreign creditors—including Japan, China, and the UK—have begun scaling back their holdings. This shift comes as borrowing costs reach their highest levels in nearly two decades, prompting questions about the long-term health of the US economy and the broader implications for international markets.
Treasury bonds function as the government’s IOUs, serving as a benchmark for global interest rates because the US has historically never missed a payment. However, the relationship between bond prices and yields is currently creating pressure. When investors sell these bonds, prices drop, which forces yields to rise. Consequently, when the government issues new debt, it must offer higher returns to attract buyers, further increasing the cost of servicing the nation’s massive financial obligations.
Foreign holdings of Treasuries saw a decline in June, continuing a trend led by Japan, the UK, and China. In March alone, Japan and China offloaded $47.7 billion and $41 billion in assets, respectively. The motivations behind these sales vary. For Japan, the pullback is largely driven by private institutions like pension funds and insurers shifting toward domestic bonds, while the Bank of Japan has been forced to manage a trade gap widened by rising oil costs linked to the conflict in Iran. China’s divestment is managed centrally as part of its state reserve strategy, and some of the UK’s reported holdings are actually assets managed on behalf of global funds that use London as a custody hub.
The financial pain for foreign holders is substantial; in March alone, they faced $142.1 billion in paper losses on existing Treasury holdings as yields climbed. This, combined with broader concerns regarding US inflation and debt levels, has made selling appear to be the more prudent choice for many investors. The situation is further complicated by the fact that the traditional safe-haven status of bonds is being tested. When the US and Israel struck Iran on February 28, Treasury yields unexpectedly rose, breaking the historical pattern where investors typically flock to bonds during times of geopolitical conflict.
In response to the mounting pressure, the US Treasury has attempted to stabilize the market through bond buybacks. On August 19, Treasury Secretary Scott Bessent announced that the department would more than double the scale of these operations, increasing them from $2 billion to at least $4 billion per session, running from September 9 through November 4. Additionally, Washington has intervened in currency markets to support the Japanese yen, aiming to reduce the necessity for Japan to liquidate its Treasury holdings.
Despite these measures, analysts remain skeptical about their long-term efficacy. Joseph Brusuelas, chief economist at RSM US LLP, described the buyback program as a “temporary salve to an open financial wound of our own making,” noting that it fails to address the underlying issues of inflation, the AI-driven borrowing boom, and the sheer scale of US debt. Fixed-income manager Kelsey Berro echoed this sentiment, telling CNBC that lower yields cannot be sustained without fundamental support. Furthermore, the Treasury’s own advisory panel has cautioned against using buybacks as a primary tool for debt management, arguing that new bond sales should remain the focus.
The fiscal outlook is increasingly strained. Interest payments on the national debt now exceed $1 trillion annually—nearly triple the 2020 figure—and have surpassed Medicare as the government’s second-largest expense. The Congressional Budget Office estimates that total debt could reach $63 trillion by 2036. This trajectory is fueled by a combination of factors, including tax cuts totaling $8.7 trillion since the Bush era, $7.6 trillion in war and Medicare spending since 2001, and the rising costs associated with an aging population. Recent pressures have also been exacerbated by war spending in Iran and a surge in tariff refunds following a Supreme Court ruling against emergency tariffs.
While most economists agree that the US is not facing bankruptcy in the traditional sense—largely because it borrows in its own currency—some experts are sounding alarms. Professors such as Steve Hanke of Johns Hopkins and former Comptroller General David Walker have argued that the nation is effectively insolvent. The Committee for a Responsible Federal Budget suggests the real risk is not an abrupt default, but a slow, debilitating decay characterized by rising costs and shrinking policy options. As of August 18, total US debt reached $40.047 trillion, with roughly $32 trillion of that figure representing debt traded in the open market, which remains the primary focus for investors watching the current sell-off. The report also notes that what the US is doing about it, and why it matters well beyond America’s borders, here’s what’s driving it. The report also notes that goods, or services to another), treasury bonds are simply the US government’s IOUs (I Owe You – a simple written acknowledgement that someone owes money. The report also notes that promising to repay them with interest, washington sells them to raise money it needs but doesn’t have on hand. The report also notes that influencing borrowing costs and asset prices far beyond the United States, that trust makes Treasuries a benchmark for global finance. The report also notes that a yield of 5%, say a bond has a face value of $100 and pays $5 a year in interest. The report also notes that the $5 payment stays the same, but it now represents a larger share of the new buyer’s cost, pushing the yield up to about 5.6%, if investors sell that bond and its price drops to $90. The report also notes that offloading $47.7B and $41B, respectively, japan and China had already sold heavily in March. The report also notes that since official data groups together very different actors, it helps to be precise about who is actually selling.